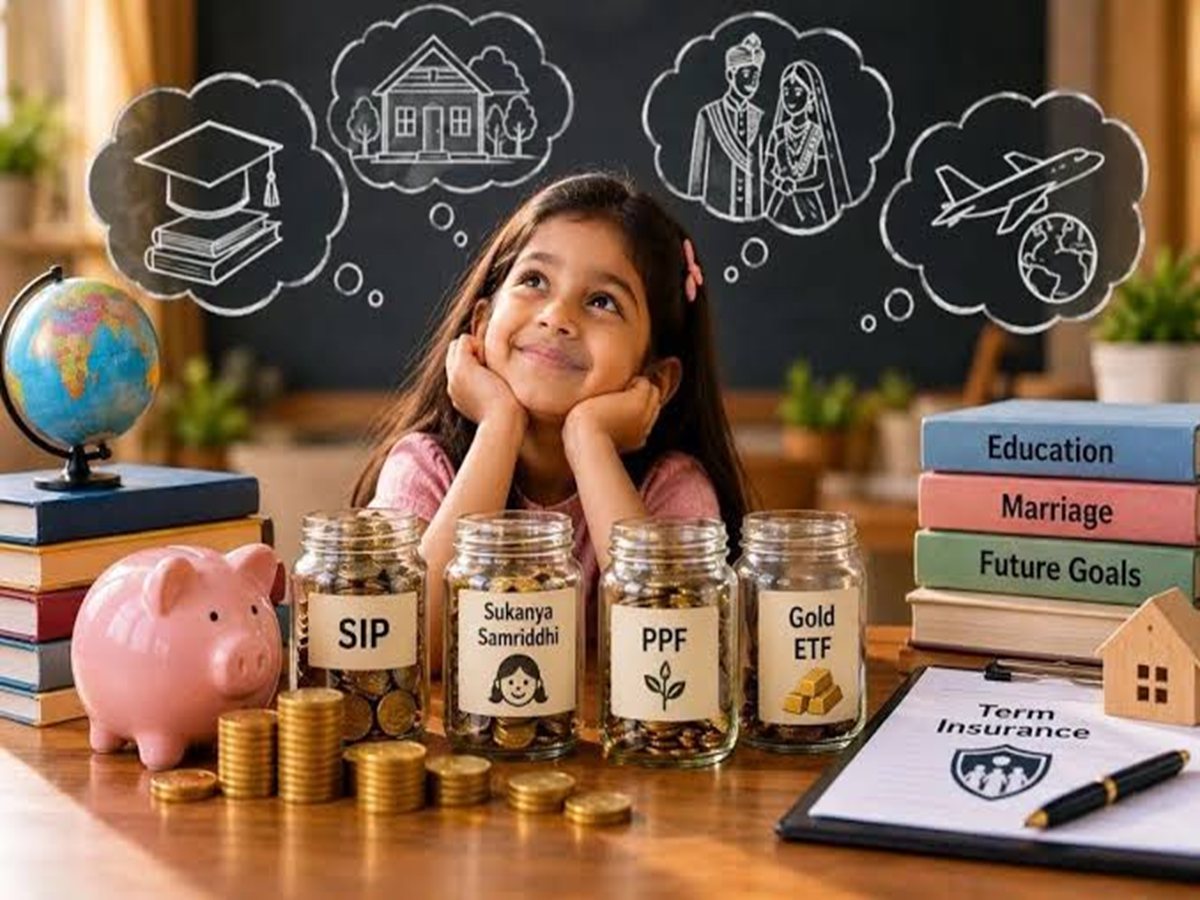
The cost of children's education is constantly rising. Given this, the biggest question parents face is where to invest for their child's future so that a substantial sum is available 15–18 years later.
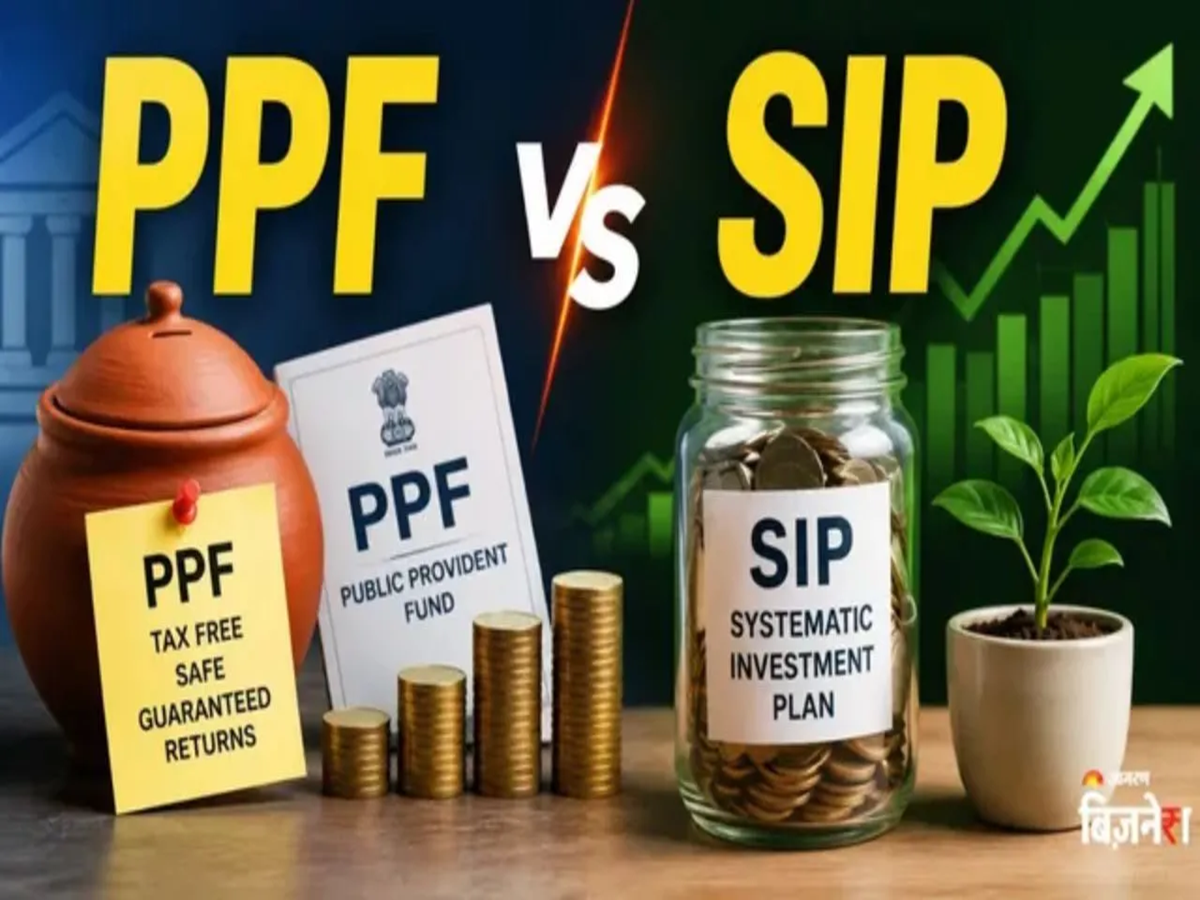
Options such as the Public Provident Fund (PPF), Sukanya Samriddhi Yojana (SSY), and mutual funds are available for this purpose. However, these schemes differ in terms of returns, withdrawal facilities, and lock-in conditions.
To understand these three options, let’s assume a parent invests ₹3,000 every month for 15 years. How much of a corpus would be created?
How much will an investment of ₹3,000 per month yield?
Monthly investment: ₹3,000
Annual investment: ₹36,000
Investment duration: 15 years
Total amount invested: ₹540,000
Now, let’s look at the potential corpus that could be accumulated through these different options:
PPF (7.1% interest): ₹9.34 lakh
Sukanya Samriddhi Yojana (8.2% interest): Approximately ₹10.30 lakh
SIP (12% return): ₹14.43 lakh
Highest potential returns with mutual funds
Assuming an average annual return of 12% on a 15-year SIP in a mutual fund, an investment of ₹3,000 per month would result in a corpus of ₹14.43 lakh.
In this scenario, the investor would have deposited a total of ₹5.40 lakh, potentially gaining around ₹9.03 lakh. The accumulated amount would be available for the child by the time they reach the age of 18.
What are the key features of PPF and Sukanya Samriddhi Yojana?
PPF is a suitable option for parents looking for a long-term investment backed by a government guarantee. It currently offers an annual interest rate of 7.1%.
Meanwhile, the Sukanya Samriddhi Yojana is designed specifically for daughters. It currently offers an annual interest rate of 8.2%. Under this scheme, an account can be opened if the daughter is under 10 years of age.
PC Social Media