Business
Ayushman Card Rules 2026: What If Your ₹5 Lakh Free Treatment Limit Runs Out? Know Your Options
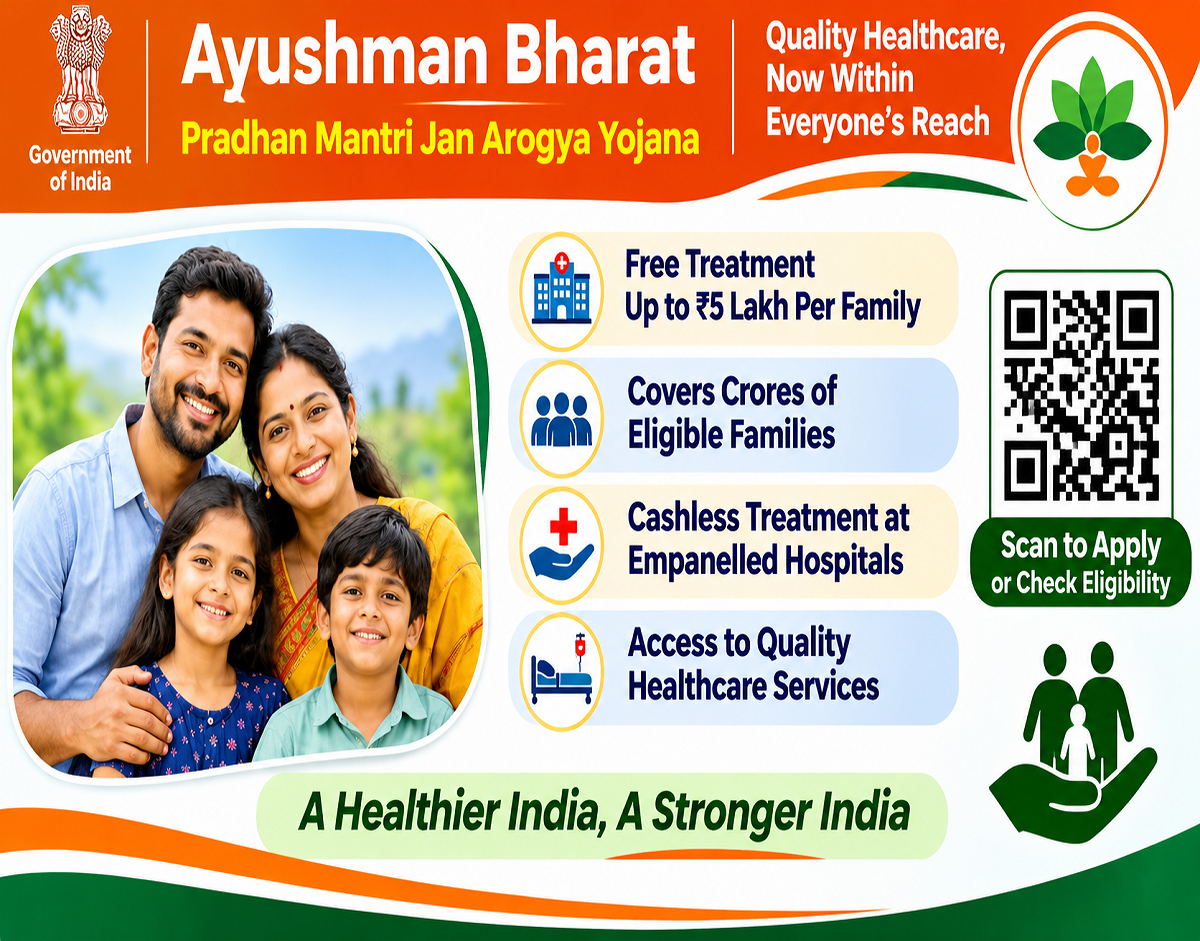
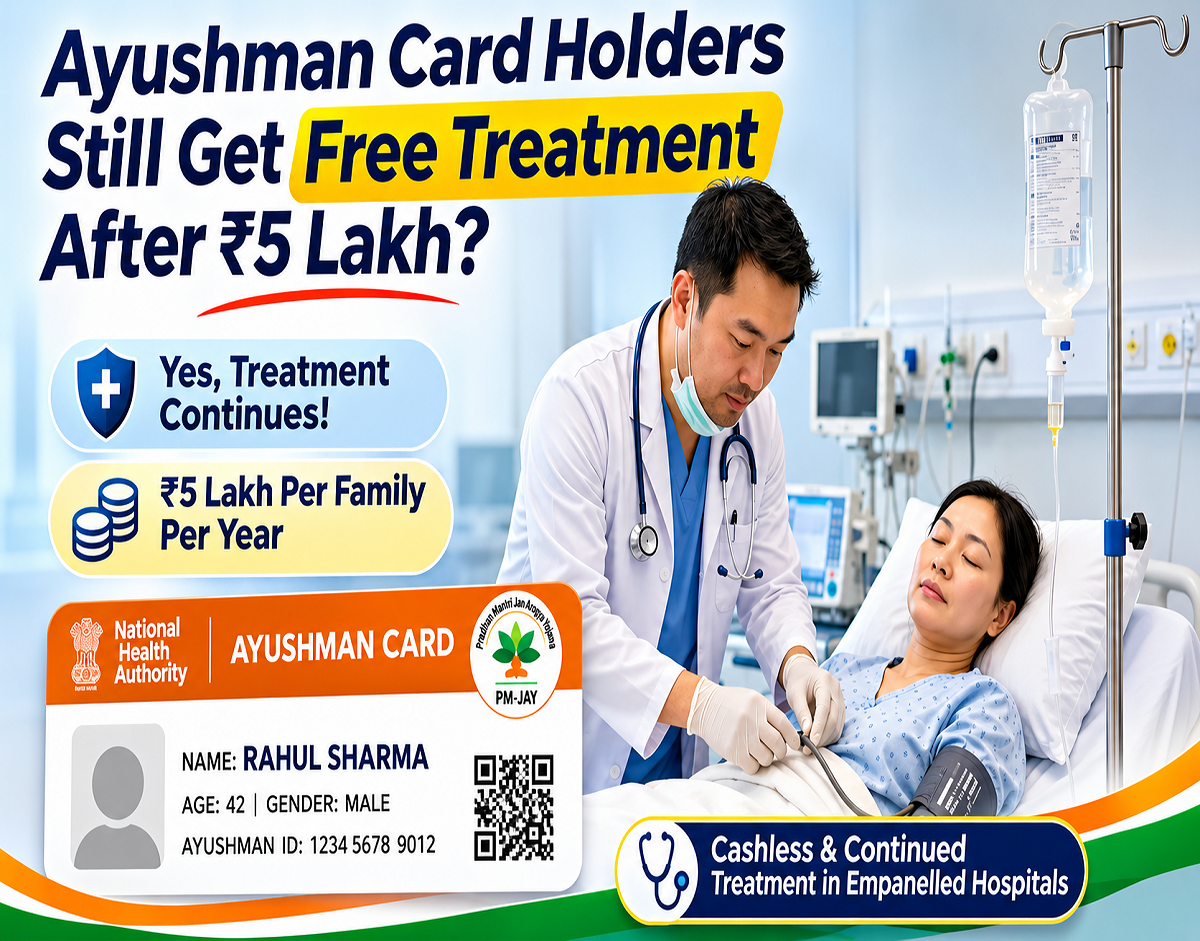
Ayushman Bharat PM-JAY Update 2026: The Ayushman Bharat Pradhan Mantri Jan Arogya Yojana (AB PM-JAY) provides health coverage of up to ₹5 lakh per eligible family each year for specified hospital treatments. The government-backed scheme is designed to help eligible households access medical care without facing the full financial burden of hospitalisation.
However, many Ayushman Card holders have an important question: What happens if the entire ₹5 lakh coverage amount is used before the annual benefit period ends? Can patients continue receiving cashless treatment, or will they have to pay additional hospital expenses themselves?
Understanding the scheme's coverage rules is particularly important for families dealing with serious medical conditions that require expensive surgeries, repeated hospital admissions or prolonged treatment.
While the standard PM-JAY benefit has a defined annual limit, additional assistance may be available through certain state-specific arrangements and other government medical support programmes, subject to eligibility and approval.
Ayushman Bharat Scheme: How Does the ₹5 Lakh Coverage Work?
Under the Ayushman Bharat PM-JAY scheme, eligible families receive health coverage of up to ₹5 lakh annually for specified secondary and tertiary hospitalisation services.
The coverage is provided on a family-floater basis, meaning the amount is shared among eligible members of the family rather than being allocated separately to each person.
For example, if one family member receives treatment costing ₹2 lakh under the scheme, the remaining ₹3 lakh may be available for other eligible treatment expenses during the same coverage period.
Similarly, if multiple family members require hospitalisation, their eligible treatment expenses are deducted from the family's available coverage amount.
The scheme is intended to reduce out-of-pocket hospital expenses for eligible beneficiaries.
Is the ₹5 Lakh Ayushman Card Limit for Each Person or the Entire Family?
One of the most common misunderstandings about the Ayushman Bharat scheme concerns the annual coverage amount.
The standard ₹5 lakh benefit is shared by the entire eligible family, not provided separately to every family member.
Here is an illustration of how the family-floater coverage works.
| Treatment Details | Amount |
|---|---|
| Total annual family coverage | ₹5,00,000 |
| First family member's treatment | ₹1,50,000 |
| Second family member's treatment | ₹2,00,000 |
| Remaining coverage | ₹1,50,000 |
This example demonstrates how different hospitalisation expenses can reduce the available family coverage.
Actual deductions depend on approved treatment packages, hospital claims and applicable scheme rules.
What Happens When the Ayushman Card's ₹5 Lakh Limit Is Exhausted?
If the entire ₹5 lakh family-floater amount has been utilised during the applicable annual coverage period, further expenses are generally not covered under the standard PM-JAY annual benefit for that period.
This means that if another family member requires treatment after the available coverage has been exhausted, the hospital cannot automatically claim additional reimbursement under the same standard coverage limit.
However, exhausting the annual benefit does not mean that the Ayushman Card is permanently cancelled.
The beneficiary's eligibility under the scheme may continue, and coverage becomes available again when the next applicable annual benefit cycle begins.
Beneficiaries should confirm their remaining coverage and renewal period with the authorised Ayushman helpdesk or State Health Agency.
Does the ₹5 Lakh Ayushman Coverage Reset Every Year?
The Ayushman Bharat scheme provides an annual coverage benefit, meaning the standard family-floater amount is renewed for the next applicable coverage cycle.
For example, if an eligible family has used its full annual coverage, a fresh benefit amount becomes available when the next coverage period begins, subject to continued eligibility and scheme conditions.
However, beneficiaries should not automatically assume that every family's coverage resets on April 1.
The applicable renewal or benefit-cycle date should be verified through the scheme's official records or the relevant State Health Agency.
This distinction is important for patients planning expensive medical procedures or ongoing hospital treatment.
Can Patients Receive Additional Financial Help After Exhausting the Limit?
In certain circumstances, patients requiring expensive medical treatment may be able to seek assistance through state-specific programmes or other government financial support arrangements.
However, additional treatment beyond the ₹5 lakh PM-JAY limit is not automatically guaranteed.
Some states may operate supplementary health coverage schemes, special assistance arrangements or separate medical relief programmes.
Availability depends on the state's policies, the patient's eligibility, the nature of the treatment and the applicable approval process.
Patients should contact the State Health Agency or the authorised Ayushman helpdesk at their hospital to determine whether additional support is available.
How to Request Additional Assistance for Serious Medical Conditions
Patients facing expensive treatments for conditions such as cancer, major cardiac diseases or organ-related complications may need financial support beyond the standard coverage.
Where a relevant state assistance mechanism exists, the following process may help:
- Contact the hospital's Ayushman helpdesk: Explain that the family's annual PM-JAY coverage has been exhausted or is nearly exhausted.
- Obtain medical documents: Collect the doctor's recommendation, diagnosis, treatment estimate and relevant hospital records.
- Contact the State Health Agency: Ask whether the state provides supplementary coverage or exceptional financial assistance.
- Submit the required application: Provide supporting documents through the authorised procedure.
- Wait for an official decision: Additional financial assistance, if available, depends on eligibility and approval.
Some programmes may involve review by designated medical or administrative authorities.
However, there is no universal rule guaranteeing additional PM-JAY coverage merely because a district official or Chief Medical Officer approves a request.
Other Government Schemes That May Help With Medical Expenses
Patients who have exhausted their Ayushman Bharat coverage may explore other assistance programmes.
Rashtriya Arogya Nidhi
The Rashtriya Arogya Nidhi is a government medical assistance mechanism intended to support eligible patients requiring treatment for specified serious illnesses.
Financial assistance depends on the programme's eligibility criteria, treatment requirements, available funding and other applicable conditions.
Patients should check the latest rules through authorised government hospitals or the relevant government department.
Chief Minister's Relief Fund
Several states operate Chief Minister's Relief Funds that may provide financial assistance to eligible individuals facing serious medical expenses.
The application procedure, income requirements, medical documentation and approval conditions differ between states.
Applicants should consult their state government's official website or designated assistance office for accurate information.
How Many Times Can You Use an Ayushman Card in One Year?
The Ayushman Bharat scheme does not generally impose a fixed annual number of hospital admissions under the standard family-floater benefit.
Eligible beneficiaries may receive treatment multiple times during the coverage period, provided the treatments are covered and sufficient benefit remains available.
For example, a family may use the scheme for more than one hospitalisation, with the approved treatment costs deducted from the available coverage.
However, the total eligible expenditure must remain within the applicable annual benefit limit unless another authorised coverage arrangement applies.
Can You Use an Ayushman Card at Any Hospital?
No. Cashless treatment under PM-JAY is generally available through hospitals empanelled under the scheme.
These include participating government and private hospitals.
Beneficiaries should verify that the hospital is empanelled and that the required treatment is covered under the applicable package.
Not every medical procedure, outpatient consultation or medicine purchase is automatically covered.
Before admission, patients should confirm the hospital's participation, treatment eligibility and remaining coverage through the authorised Ayushman helpdesk.
How to Check Your Remaining Ayushman Card Coverage
Beneficiaries who want to know how much coverage remains should contact an authorised Ayushman helpdesk at an empanelled hospital.
The helpdesk can assist with eligibility verification, available benefit information and applicable treatment packages.
Beneficiaries can also use official Ayushman Bharat services for scheme-related information.
Ayushman Bharat PM-JAY Helpline
14555
For eligibility, hospital information, grievances and assistance with scheme-related questions.
Copy Helpline Number
Beneficiaries may also visit the official Ayushman beneficiary portal for supported services.
Important Things Ayushman Card Holders Should Remember
Families covered under PM-JAY should understand that the ₹5 lakh amount is an annual family-floater benefit.
It is important to monitor the available coverage, particularly when multiple family members require hospitalisation.
Patients should also confirm whether the proposed treatment falls under the approved package list and whether the hospital is authorised to provide it.
If the coverage is exhausted, families should explore state-specific assistance programmes rather than assuming that additional free treatment will automatically be approved.
They should also avoid paying unauthorised charges for services that are covered under an approved cashless treatment package.
Ayushman Bharat ₹5 Lakh Limit: Final Takeaway
The Ayushman Bharat PM-JAY scheme provides important financial protection to eligible families through annual health coverage of up to ₹5 lakh.
However, the standard benefit is shared among family members, and once the available amount has been fully utilised, additional treatment expenses are generally not payable under the same annual coverage limit.
Eligible families can receive renewed coverage in the next applicable benefit period, while some patients may qualify for additional assistance through separate state or government programmes.
The key takeaway: If your Ayushman Card's ₹5 lakh coverage is exhausted, contact the hospital's Ayushman helpdesk or State Health Agency to verify your remaining benefits and explore any available supplementary assistance. Additional financial support depends on the relevant scheme's rules and is not guaranteed.